Paying a Mexican Company from the U.S.: W-8BEN-E, Withholding and Form 1042-S
Paying a Mexican company from the U.S.? Learn how W-8BEN-E, income sourcing, withholding and Form 1042-S fit into a defensible payment process.
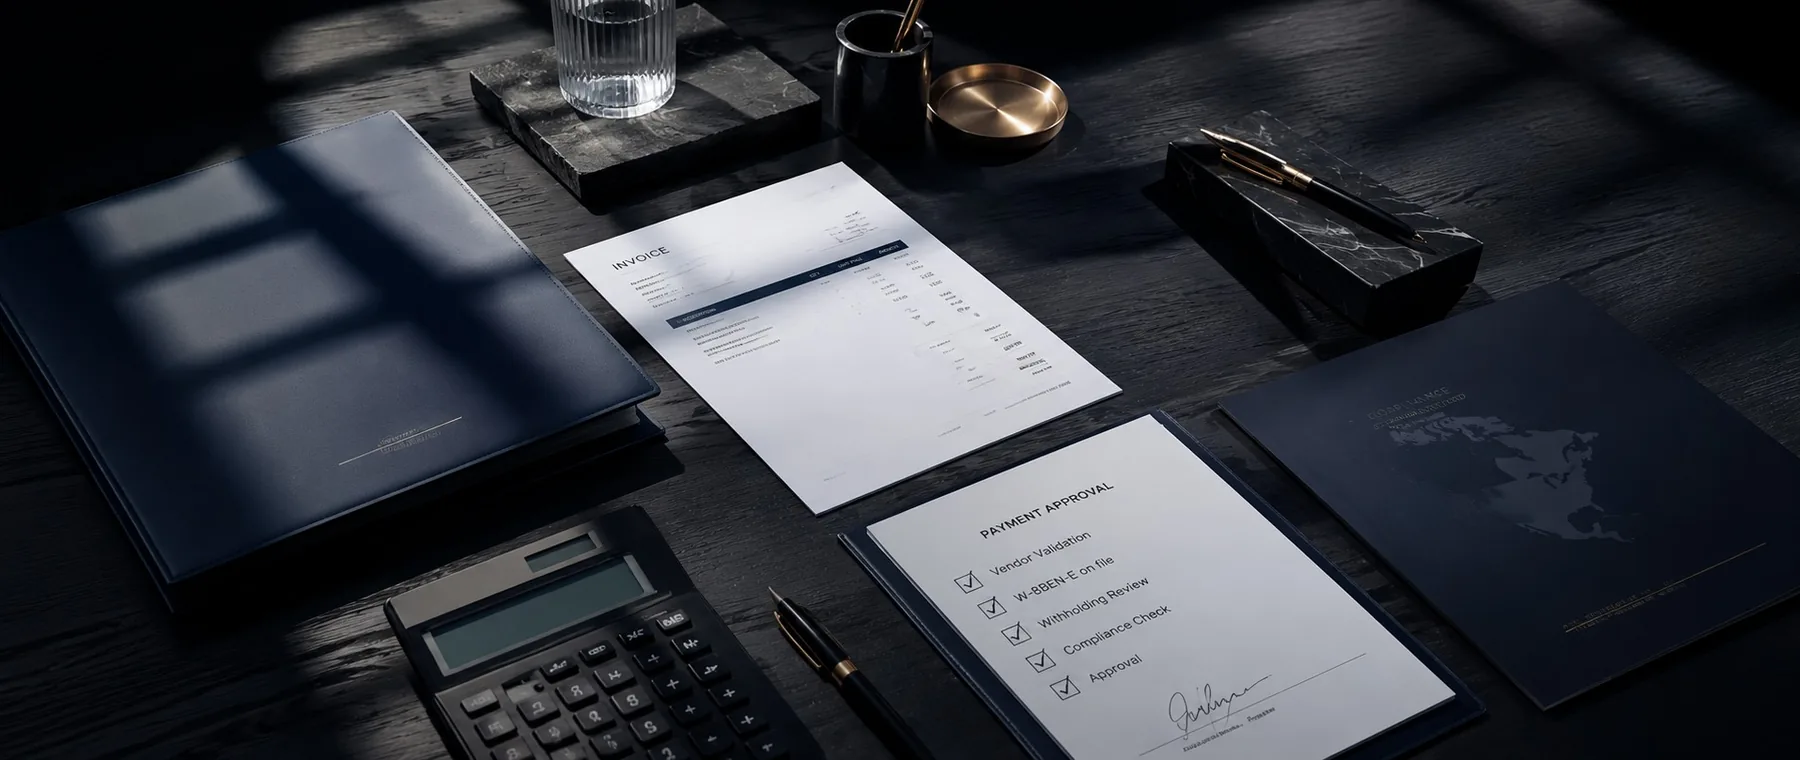
Before a U.S. company pays a Mexican company, it should identify the foreign payee, classify what the payment is for, determine where any services were performed, obtain the appropriate W-8 documentation, and then decide whether U.S. withholding or Form 1042-S reporting applies. The payee's country or bank account alone does not determine the result.
Cross-border vendor payments often become tax questions too late. Accounts payable receives an invoice, the business wants it released, and only then does someone ask whether the vendor should have supplied a tax form or whether U.S. withholding applies.
A cleaner process moves those questions upstream. The payment should be understandable before the wire is approved: who is being paid, what generated the payment, where the underlying activity occurred, and what documentation supports the tax treatment. For companies with recurring activity between both countries, this payment control belongs inside a broader U.S.–Mexico accounting and tax coordination model rather than sitting only with accounts payable.
Start with what the payment actually represents
“Payment to Mexico” is not a tax category. A U.S. company may be paying a Mexican entity for consulting, software, a royalty, interest, rent, inventory, a reimbursement or another type of transaction. The classification matters because different categories can follow different source, withholding and reporting rules.
The IRS's guidance for U.S. withholding agents makes the same point operationally: foreign vendors should first be identified as foreign, and the payer should then determine whether the expense is the type of income that enters the U.S. withholding regime. The IRS also recommends obtaining valid foreign-status documentation from newly used foreign vendors before payment rather than trying to reconstruct the file later.
What Form W-8BEN-E does—and what it does not do
Form W-8BEN-E is used by foreign entities to document their status for U.S. withholding and reporting purposes. For a Mexican corporate vendor, that can make the form an important part of vendor onboarding.
But the form is documentation, not a universal exemption certificate. Receiving a W-8BEN-E does not automatically establish that every payment to that vendor is foreign-source, exempt from withholding or outside Form 1042-S reporting.
The payer still has to understand the transaction. The appropriate W-8 form can also vary when, for example, the payee is acting as an intermediary or claims that the income is effectively connected with a U.S. trade or business.
For services, where the work was performed can change the answer
Service payments are where finance teams often rely on the wrong fact. The location of the bank account, the customer's address or the place where the contract was signed does not necessarily establish the source of service income.
IRS guidance states that the place where personal services are performed generally determines the source of that income. If work is performed partly inside and partly outside the United States, an allocation may be required based on the applicable sourcing rules.
For a U.S. company hiring a Mexican consulting or technical-services firm, the operational question therefore becomes: were the services performed from Mexico, in the United States, or in both places?
The IRS's withholding-agent FAQ specifically tells payers reviewing foreign-vendor service payments to examine invoices, engagement letters, contracts and related documentation to determine whether any services were performed in the United States. It also notes that if the source cannot be determined at the time of payment, presumption rules can cause the payment to be treated as U.S.-source for withholding purposes.
When U.S.-source income enters the withholding analysis
U.S.-source income paid to a foreign person can enter the chapter 3 withholding regime. The statutory rate for applicable U.S.-source fixed or determinable annual or periodical income is generally 30% unless an exception or an applicable treaty supports a different result.
That does not mean every payment to a Mexican company should be withheld at 30%. It means the U.S. payer should be able to document why the payment is or is not within the withholding regime.
Mexico is a U.S. income-tax treaty partner. Treaty benefits can reduce or eliminate withholding in qualifying circumstances, but the result depends on the type of income, the beneficial owner and the requirements of the relevant treaty provision. A Mexican address by itself is not enough.
When the income is genuinely foreign-source, IRS guidance explains that it is normally outside U.S. nonresident withholding and normally does not require Form 1042-S reporting. That is why documenting where the activity occurred can be just as important as collecting the foreign-status form.
Withholding and Form 1042-S are related—but not identical
One of the most common process errors is assuming that “no tax withheld” means “nothing to report.” That is not always correct.
The 2026 Instructions for Form 1042-S identify U.S.-source payments to foreign persons that remain reportable even when an exemption or treaty position affects the amount actually withheld. The finance team therefore needs two conclusions: what withholding applies, and what information reporting applies.
That distinction is particularly useful when designing accounts-payable controls. The payment system should not treat the withholding percentage as the only tax field that matters.
A defensible foreign-vendor payment workflow
The goal is not to turn accounts payable into international tax counsel. It is to make sure the people approving the payment collect the facts needed for a supportable decision.
| Question | What the file should establish |
|---|---|
| Who is the payee? | Legal name, country, entity status and whether the vendor is related or unrelated to the U.S. payer. |
| What is being purchased? | Services, goods, royalties, interest, rent, reimbursement or another clearly described payment. |
| Where did the activity occur? | For service arrangements, whether work was performed in Mexico, the United States or both. |
| What tax documentation exists? | The appropriate valid W-8 documentation and any information supporting a treaty or other tax position. |
| Does withholding apply? | The rate, legal basis and calculation—not simply a default percentage copied from another vendor. |
| Does reporting apply? | Whether Form 1042-S or another information-reporting treatment is required for the payment. |
| Can the conclusion be reproduced later? | Invoice, contract, sourcing facts, withholding certificate and decision retained in a coherent vendor/payment file. |
Three process failures worth preventing
Waiting until the invoice is due. If the tax documentation is requested only after the business expects the wire to be released, a compliance question becomes an operational emergency.
Collecting the W-8 but ignoring the transaction. A foreign-status certificate does not explain whether the payment is for services, interest, royalties or another category.
Never revisiting the vendor file. A Mexican provider may begin by performing all work remotely and later send personnel into the United States, license intellectual property or change the scope of its engagement. The original conclusion may no longer describe the current arrangement.
When the Mexican company is related to the U.S. payer
A related-party payment adds another layer. In addition to sourcing, withholding and reporting, the group may need to address transfer pricing, intercompany documentation and whether the charge reflects the actual functions performed between the entities.
That is a different search intent from ordinary foreign-vendor onboarding. If the Mexican company is part of the same group, continue with our guide to U.S.–Mexico intercompany service fees and documentation rather than treating the charge like an unrelated vendor invoice.
Common questions about paying Mexican vendors
Does every Mexican company need to give a U.S. payer Form W-8BEN-E?
A U.S. withholding agent generally needs reliable documentation of a foreign vendor's status before relying on that status for withholding purposes. W-8BEN-E is commonly used by foreign beneficial-owner entities, but the correct W-8 form depends on the payee's role and the nature of the income.
If all services are performed in Mexico, is U.S. withholding required?
Service income is generally sourced where the services are performed. IRS guidance explains that foreign-source income is normally outside U.S. nonresident withholding and normally does not require Form 1042-S reporting. The payer should still document the service location and confirm that the payment has been characterized correctly.
Does a W-8BEN-E mean Form 1042-S is never required?
No. W-8BEN-E documents the foreign entity's status and may support a treaty claim, but U.S.-source amounts can still be reportable on Form 1042-S even when the applicable withholding is reduced or eliminated.
What if the Mexican vendor performs work in both Mexico and the United States?
The sourcing analysis may need to allocate the service income between U.S. and foreign activity under the applicable rules. Contracts, invoices, work records and travel or project information can become important evidence for that allocation.
A payment process that management can defend later
The strongest control is not an extra tax checklist added after the fact. It is a vendor-onboarding and payment process that captures the right facts before funds move.
For recurring U.S.–Mexico activity, that means connecting accounts payable, tax documentation and cross-border review around the same transaction. When the company can trace the payment from contract to invoice to sourcing conclusion to withholding and reporting, the tax treatment becomes easier to explain—and much harder to lose inside a year-end cleanup. The broader operating model is explained through the USA Desk’s U.S.–Mexico Cross-Border Advisory.
Official sources and further reading
Primary sources used to verify the tax concepts in this article. Links open on the IRS website.
This article provides general information for business planning and does not replace analysis of a specific payment, tax position or treaty claim.