Intercompany Loans From a Mexican Parent to a U.S. Subsidiary: Interest, Withholding and Documentation
How to document a Mexican parent–U.S. subsidiary loan: debt terms, arm’s-length pricing, treaty withholding, Form 1042-S and monthly reconciliation.
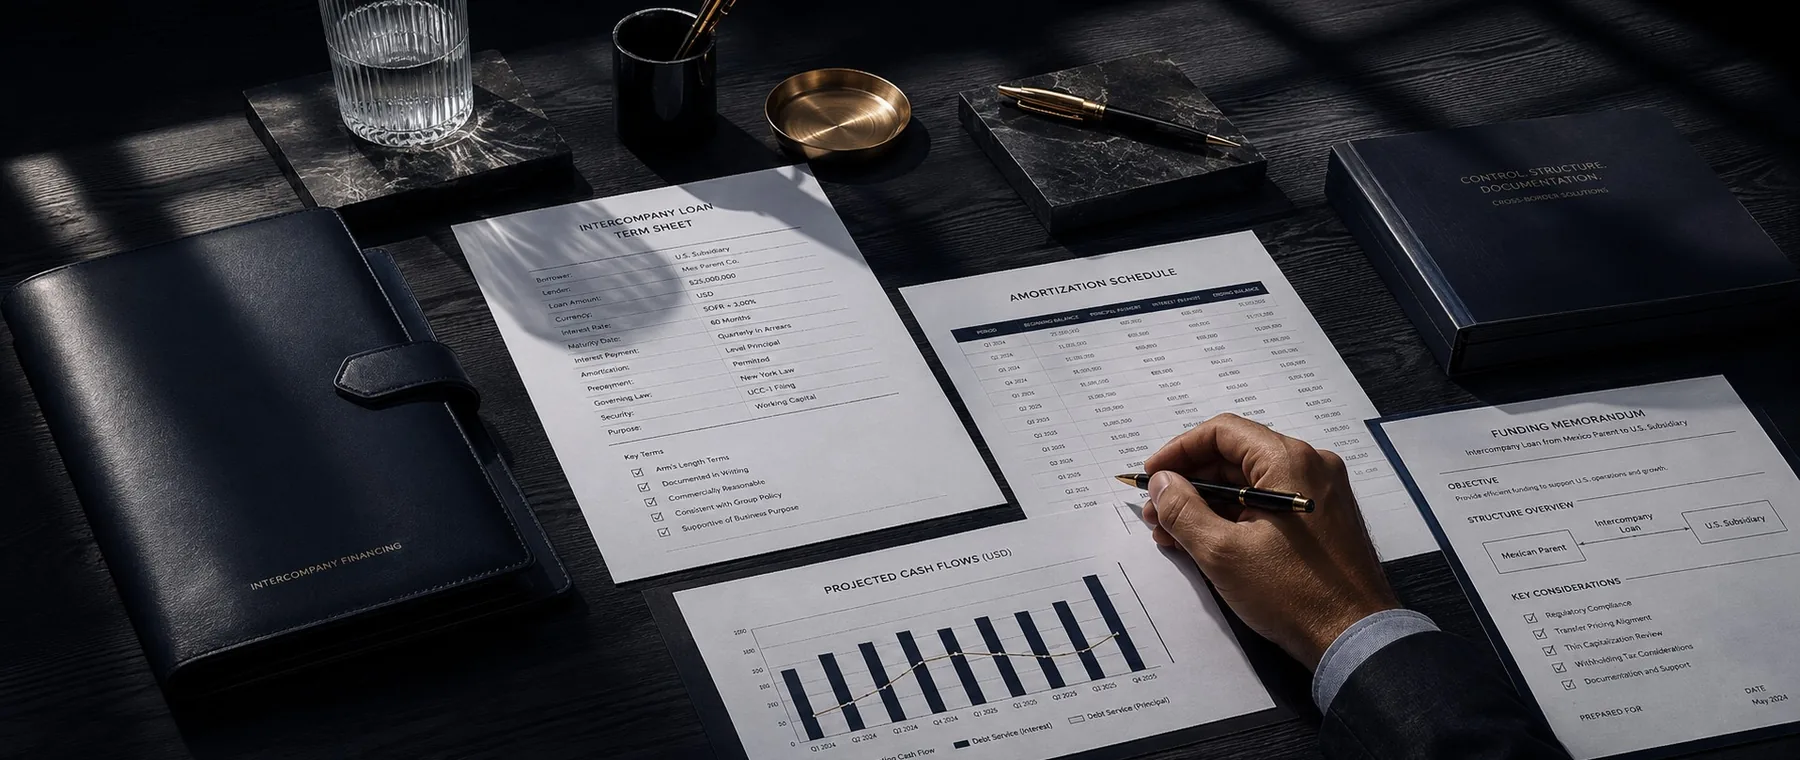
If a Mexican parent funds a U.S. subsidiary as debt, the group should document the loan terms, support the interest rate, maintain a principal-and-interest roll-forward, determine the U.S. withholding and treaty position before interest is paid or credited, and coordinate Form 1042/1042-S reporting with the accounting records.
International groups often fund a new U.S. operation incrementally. Cash is sent when the subsidiary needs payroll, inventory or working capital, and the accounting team posts each transfer to “due to parent.” The balance grows long before anyone decides what the arrangement actually is.
That is the point where a simple treasury habit can become a tax and reporting problem. If the funding is intended to be debt, the terms and accounting should behave like debt from the beginning. A coordinated cross-border finance and tax process helps keep the funding documentation, accounting treatment, withholding analysis and reporting on the same set of facts.
Decide what the funding is before it becomes a permanent balance
A transfer from a parent to a subsidiary can represent paid-in capital, a formal loan, settlement of another intercompany transaction or another type of funding. The bank description does not decide the tax character.
If the intended relationship is a loan, the file should identify the lender and borrower, principal, currency, interest terms, maturity or repayment mechanics, payment frequency and business purpose. The exact documentation depends on the transaction and governing law, but ambiguity should not be the default operating model.
The interest rate is a controlled-transaction question
A parent-subsidiary loan is a related-party financial transaction. Under Section 482, the IRS applies the arm's-length standard to controlled transactions. The transfer-pricing analysis should therefore support the rate and terms used rather than treating the agreement as proof that the number is correct.
Relevant facts can include the currency, term, borrower credit characteristics, security, subordination, repayment capacity and market context. The point is not to create a complex model for every advance; it is to be able to explain why the financing terms are reasonable for the transaction actually entered into.
If the recurring intercompany charge is for services rather than financing, keep it out of the loan schedule. The separate guide to U.S.–Mexico intercompany service fees explains the service-side documentation and allocation controls.
Interest paid to the Mexican parent requires a treaty-specific withholding review
U.S.-source interest paid to a foreign person can fall within the U.S. chapter 3 withholding regime. Domestic law generally starts with a 30% rate for applicable U.S.-source FDAP income unless an Internal Revenue Code provision or an income-tax treaty supports a lower result.
The U.S.–Mexico income tax convention has a more detailed interest article than a single “Mexico rate.” Article 11 lists a 4.9% ceiling for certain bank, insurance and regularly traded debt categories; 10% for specified categories including certain interest paid by banks and qualifying credit sales of machinery and equipment; and 15% for all other cases, subject to the article's conditions and other treaty provisions.
A foreign corporate lender claiming treaty benefits generally documents its status with the appropriate withholding certificate, commonly Form W-8BEN-E when it is the beneficial owner. The form should be obtained and validated before the payment or credit for which the treaty position is being used.
Withholding, Form 1042-S and Form 1042 belong to the same payment workflow
Form 1042-S is used to report specified U.S.-source income paid to foreign persons and amounts withheld under chapters 3 and 4. The IRS's 2026 instructions also explain that reportable amounts may need a Form 1042-S even when a treaty or Code provision reduces or eliminates the tax actually withheld.
When a Form 1042-S is filed, the related annual withholding return, Form 1042, also enters the process. That makes the interest-payment file more than a wire instruction: finance needs the gross income, recipient documentation, rate, exemption or treaty code as applicable, withholding, payment and reporting to agree.
Withholding and interest deductibility are separate questions
Determining the withholding rate on interest paid to Mexico does not establish how much interest the U.S. borrower can deduct. Section 163(j), when applicable, can limit the deduction for business interest expense.
The IRS updated its Section 163(j) FAQs in August 2026. They explain that the limitation, when it applies, is calculated by reference to business interest income, 30% of adjusted taxable income and floor-plan financing interest, with exceptions and additional rules depending on the taxpayer.
For a finance team, the operational lesson is simpler: the outbound withholding analysis and the U.S. interest-deduction analysis should be tracked separately. A correct treaty rate does not prove deductibility, and a deductible expense does not prove the withholding result.
Maintain a loan roll-forward that both entities can reproduce
| Loan movement | U.S. subsidiary | Mexican parent |
|---|---|---|
| Opening principal | Loan payable | Loan receivable |
| New advances | Increase payable | Increase receivable |
| Principal repayments | Reduce payable | Reduce receivable |
| Interest accrued | Interest expense/payable, subject to applicable rules | Interest income/receivable under the parent's accounting and tax framework |
| Interest payment | Gross payment, withholding and cash settlement | Gross income, tax information and net cash received |
| Closing principal | Ending payable supported by the schedule | Ending receivable supported by the same transaction history |
Functional-currency amounts can differ after translation. The underlying transaction history should not. If one side has four advances and the other has three, the difference is operational, not foreign exchange.
Do not let accrued interest exist only in the tax workpapers
If the agreement provides for interest but accounting only recognizes it when cash moves, the legal terms, books and tax reporting can drift apart. A recurring close should determine the appropriate accrual treatment and update the loan schedule consistently.
The same discipline helps with withholding events. Depending on the relevant rules, a tax “payment” can occur even when there is no obvious net cash transfer, so the tax team should not be introduced only when treasury schedules a wire.
Debt characterization deserves attention before the first repayment
A document titled “loan agreement” does not by itself settle every debt-versus-equity issue. The U.S.–Mexico treaty protocol expressly recognizes that domestic law can characterize a payment as a dividend or limit its deductibility in certain financing situations.
That is one more reason to align the economics, documentation and behavior of the arrangement. If the group intends equity, document equity. If it intends debt, operate the funding as debt rather than leaving an indefinite current-account balance to be characterized later.
The distinction also matters when cash eventually returns to Mexico. A principal repayment, interest payment and shareholder distribution are not the same transaction. Our separate guide to dividends from a U.S. subsidiary to a Mexican parent addresses the distribution workflow.
Common questions about Mexican parent–U.S. subsidiary loans
Is the U.S.–Mexico treaty interest rate always 10%?
No. Article 11 contains several categories. It lists 4.9% for specified bank, insurance and traded-debt situations, 10% for certain other specified cases, and 15% for all other cases, subject to treaty eligibility and the facts of the payment.
Does the U.S. subsidiary need a W-8BEN-E from its Mexican parent?
A foreign entity that is the beneficial owner and claims treaty benefits generally uses Form W-8BEN-E to document foreign status and the treaty claim. The appropriate form depends on the recipient's status and role, so it should be validated before relying on a reduced rate.
Can the companies simply net interest against other intercompany balances?
Net settlement may be operationally possible, but the gross components should remain traceable. Interest, services, principal and distributions can have different accounting, withholding and reporting treatment; netting should not erase their individual character.
Should the loan be reconciled monthly?
For a recurring or material balance, a monthly roll-forward is a strong finance control. It lets both entities identify missing advances, repayments, interest accruals, FX differences and withholding entries before year-end.
Treat the loan as one finance-and-tax process
Before interest leaves the United States, management should know what the debt is, how the rate was supported, whether both entities agree on the balance, which treaty provision is being relied on, what withholding applies and how the payment will be reported.
Those questions connect treasury, tax and accounting around the same financing decision. The USA Desk’s cross-border advisory model is designed for that kind of coordinated U.S.–Mexico operating issue.
Official sources and further reading
This article is general information, not a conclusion about a particular financing. Treaty eligibility, debt characterization, withholding and deductibility depend on the facts and applicable law.